

In-depth evaluation
October 3, 2024
Data supply: U.S. Energy Information Administration, Short-Term Energy Outlook (STEO), September 2024
Note: The Electric Reliability Council of Texas (ERCOT) defines giant versatile load as any facility drawing energy from the grid with an anticipated peak demand capability of 75 megawatts or extra.
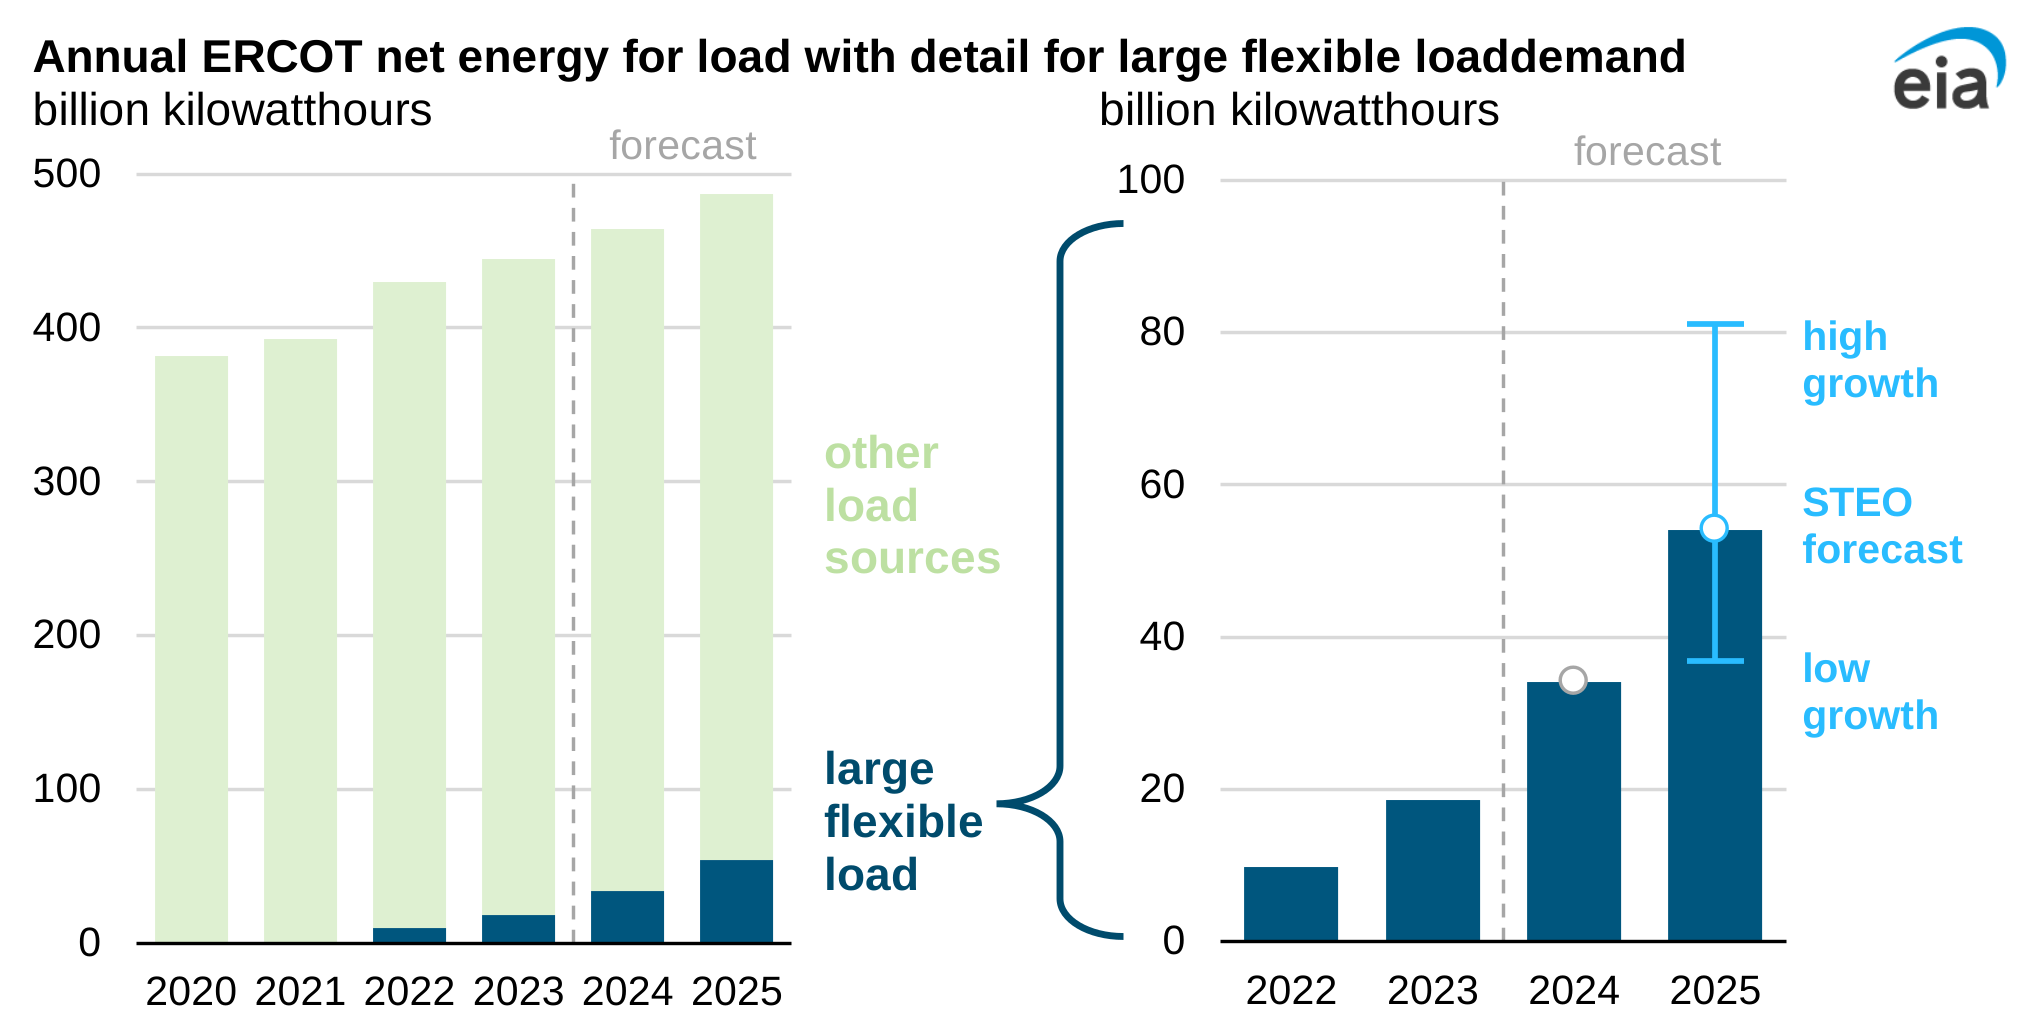
In the expansive tapestry of the United States’ energy panorama, Texas stands out as a burgeoning epicenter of electrical energy consumption. Here, the Electric Reliability Council of Texas (ERCOT) diligently oversees a staggering 90% of the state’s energy grid. The roots of this escalating demand are buried deep throughout the speedy development of large-scale computing services—assume colossal information facilities and the insatiable urge for food of cryptocurrency mining operations—although the long run trajectories of their energy consumption are riddled with uncertainty. Our newest Short-Term Energy Outlook (STEO) foretells a putting surge in electrical demand from what ERCOT categorizes as large flexible load (LFL) clients, predicting an upward leap to 54 billion kilowatt-hours (kWh) in 2025—a jaw-dropping improve of practically 60% from the projections for 2024. Impressively, this ascending demand from LFL clients is poised to command a noteworthy 10% of the full anticipated electrical energy consumption traversing the ERCOT grid in the forthcoming yr.
These large services (with their voracious appetites for electrical energy) not solely require appreciable energy to function their intricate computing apparatuses, however additionally they expend immense portions to keep up an optimum cooling atmosphere. Remarkably, a few of these behemoths eat energy on par with that of a mid-sized energy plant. In a proactive response to this burgeoning want, ERCOT initiated a program in mid-2022 designed to meticulously vet potential LFL clients, particularly concentrating on these with an anticipated peak demand capability of 75 megawatts (MW) or higher, all to uphold the integrity of grid reliability. The LFL Task Force diligently disseminates standing updates, shedding gentle on permitted capacities and anticipated forecasts for the approaching years.
Interestingly, a subset of those gargantuan load services—primarily cryptocurrency mining operations alongside information facilities and varied industrial entities—has entered into voluntary curtailment agreements with ERCOT. This association permits them to briefly dial down their energy consumption throughout these crucial junctures characterised by skyrocketing system demand or dwindling generator availability. Such flexibility permits LFL services to actively take part in ERCOT’s energy and ancillary service markets. The implications of this adaptability are vital, probably mitigating a number of the stress that speedy electrical energy demand development imposes on the ERCOT framework.
Utilizing real-time insights from ERCOT concerning the present and projected LFL demand, we meticulously craft our STEO forecasts regarding regional electrical load dynamics. It is anticipated that by the shut of 2025, ERCOT could have sanctioned operations accounting for 9,500 MW of LFL demand, marking a staggering 73% surge from the present approvals (5,479 MW of which 1,570 MW has been sanctioned in the previous yr alone).
Historically, LFL clients have averaged round 65% utilization of their totally permitted capability. For the needs of our STEO, we assume a static day by day demand reflective of this utilization fee, thus translating the anticipated 2025 capability into an estimated complete of 54 billion kWh for LFL in the upcoming yr. This burgeoning electrical energy consumption from expansive computing and industrial entities bolsters our projection that ERCOT’s load throughout all buyer segments will swell by 5% from 2024 to 2025.
Uncertainty Looms Over Future Large-Load Demand
Yet, amidst this optimistic outlook, a cloud of uncertainty hangs over the long run demand ranges of large-load customers. A latest ERCOT status update from early September highlights that formidable tasks representing a staggering 26,500 MW of LFL capability are angling for operational standing by 2025. This formidable tally encompasses round 2,000 MW earmarked for tasks but to submit formal plans, coupled with over 12,000 MW tied to tasks presently mired in ERCOT’s approval maze. Given the customary timelines for approval, it’s conceivable that these tasks won’t materialize by the tip of subsequent yr.
In a bid to understand the potential repercussions of fluctuating large-load electrical energy demand on energy era and wholesale pricing inside ERCOT, we launched into modeling two divergent eventualities, every resting on distinct assumptions concerning the 2025 LFL capability. To set up a comparative framework, we juxtaposed the outcomes in opposition to the September STEO forecast, serving as a baseline. In all three eventualities, we function below the premise that LFL services will play ball—scaling again their electrical energy consumption when wholesale energy costs soar previous $100 per megawatthour (MWh). However, the precise diploma of curtailment noticed could diverge sharply from these assumptions, hinging totally on the perceived worthiness of the incentives by the large-load clientele.

Potential delays in the approval course of for large-load tasks or hiccups in builders’ timelines might stifle the anticipated new demand from these undertakings in the approaching yr. Within our low-growth situation, we hypothesize that no new LFL capability will emerge subsequent yr past what we challenge to be purposeful on the finish of 2024 (6,500 MW). This assumption interprets right into a modest forecast of roughly 37 billion kWh of LFL electrical energy consumption in 2025—a stark 32% dip from our baseline forecast of 54 billion kWh.
On the flip aspect, a situation the place ERCOT accelerates its approval course of might unleash a torrent of latest tasks from the LFL queue at an astonishing velocity. Our high-growth situation presupposes that round 14,200 MW of LFL capability might be purposeful by subsequent yr’s conclusion, prompting an formidable forecast of 81 billion kWh of electrical energy consumption from LFL clients in 2025—an exhilarating 50% leap above the baseline STEO assumption.
In our foundational September STEO, we predict that ERCOT’s electrical energy load will climb by 5% in complete throughout all buyer classes, escalating from 464 billion kWh in 2024 to 487 billion kWh in 2025. However, in our low-growth projection, general ERCOT load would merely inch up by 1% subsequent yr, contrasting sharply with our high-growth situation, which anticipates a vigorous 10% elevation. In each low- and high-growth frameworks, we keep fixed parameters for all different variables, corresponding to generator gas prices and non-LFL concerns, mirroring the baseline forecast.
The Ramifications of Growing Demands on Power Generation
As we delve deeper, we discover that natural gas reigns because the dominant pressure in ERCOT’s electrical energy era, accounting for a considerable 45% of the area’s energy combine in 2023. Across all three eventualities, we presuppose that current and potential producing capacities stay unchanged. However, the myriad assumptions concerning future electrical energy demand wield substantial affect over natural gas era. In apply, the electrical energy sector might adapt to projected demand ranges by augmenting capability gleaned from different era sources.
In our September STEO, we foresee a dip in annual natural gas-fired era inside ERCOT—projecting a lower of 5% between 2024 and 2025, culminating in a complete of 198 billion kWh. However, our situation laden with sturdy development in large-load demand signifies a possible uptick of 8% extra natural gas-fired era in 2025 in comparison with the baseline, hitting 213 billion kWh. Conversely, our low-growth situation suggests a 12% decline in natural gas era relative to the baseline.

Data supply: U.S. Energy Information Administration, Short-Term Energy Outlook, September 2024
Note: ERCOT=Electric Reliability Council of Texas
The swiftest-growing contributor to new electrical producing capability in the United States is undeniably solar energy, with the lion’s share of this development unfolding dramatically in Texas. Our foundational STEO anticipates a unbelievable 54% leap in photo voltaic era inside ERCOT by the electrical energy sector, culminating in a powerful 67 billion kWh in 2025. Solar energy, characterised by its on-demand dispatch means, lacks the operational prices that bathroom down fossil-fueled mills. It will be curtailed seamlessly to alleviate grid congestion or when electrical energy wants plummet throughout particular time slots. Notably, in 2023, round 3% of solar output in ERCOT confronted curtailment. In our high-growth situation, we predict a further 2% improve in photo voltaic era in comparison with the baseline in 2025, as curtailed output dwindles.
Coal, which represented 14% of ERCOT era in 2023, stands as one other pivotal energy supply that will pivot below various assumptions about electrical energy demand developments. Like natural gas, coal showcases a extra responsive era sample, making it inclined to shifts in demand that would decrease or elevate coal-fired era ranges. In our low-growth situation, we anticipate a lower of 5% for ERCOT coal-fired era in 2025 versus the STEO baseline forecast of 62 billion kWh, whereas our high-growth situation envisions a 12% escalation.

Data supply: U.S. Energy Information Administration, Short-Term Energy Outlook, September 2024
Note: ERCOT=Electric Reliability Council of Texas
Unpredictable Large-Load Demand and Its Influence on Wholesale Power Prices
The rippling results of unsure future electrical energy consumption are poignantly illustrated in the realm of wholesale energy pricing—a telling barometer of the stability between provide and electrical energy demand. The STEO employs common settlement level costs (SPP) throughout peak hours on the North zone hub, which contains the colourful Dallas-Fort Worth metropolitan space, as a proxy for ERCOT’s consultant wholesale costs. Our base case STEO anticipates that wholesale energy costs in ERCOT for 2025 will hover round $27/MWh—an astonishing 22% plunge from our projected wholesale value for 2024, a decline pushed predominantly by anticipated decrease gas prices for natural gas alongside the burgeoning inflow of photo voltaic era.
In a situation reflecting subdued development in large-load demand, we challenge an 11% discount in forecasted wholesale energy costs for 2025 in comparison with the bottom case STEO prediction. Conversely, in the high-growth situation, costs might escalate by 17% relative to the baseline. Notably, probably the most vital discrepancies from the baseline situation emerge prominently in the course of the scorching summer time months. In these durations, LFL demand was curtailed for under 10 hours throughout the high-growth and base eventualities, with common cuts amounting to 23% of LFL demand in the high-growth projection and 13% in the bottom case throughout these peak hours.

Data supply: U.S. Energy Information Administration, Short-Term Energy Outlook (STEO), September 2024
Note: ERCOT=The Electric Reliability Council of Texas
With an eye fixed towards the evolving panorama of demand, ERCOT devised its LFL program aimed toward putting a fragile stability amid probably sturdy development in electrical energy consumption. By mandating challenge approvals and selling voluntary demand curtailments when wanted, the LFL framework strives to stave off the specter of wholesale energy costs hovering precariously excessive—upwards of $1,000/MWh, or extra. Further, Texas is exploring multifaceted methods to accommodate the projected escalation in energy demand stemming from expansive computing installations, together with initiatives just like the Texas Energy Fund, focused at fostering the event of latest dispatchable producing capability.
Principal contributor: Tyler Hodge